Fall is a natural moment to line up the money side of a home goal—whether you’re shopping, refinancing, or just stress-testing what you can carry. This is a practical checklist: what to gather and what to ask. It is not a market forecast.
Separate the moving parts (income, debts, reserves, lender quote)
Treat these as four different dials:
- Income — what you can document (paystubs, W-2s, or other lender-accepted proof)
- Debts — monthly obligations that show up on a credit report or application
- Reserves — cash you keep after closing costs / a down payment (your cushion)
- Lender quote — a real rate/payment range for your credit, loan type, and timing—not a headline average
Buying or refinance capacity stays personal. National headlines don’t set your payment.
What to gather before fall showings or a refinance chat
Before you book showings—or a refinance conversation—pull a simple folder:
- Recent paystubs / income docs your lender will want
- A list of monthly debts (cards, auto, student loans)
- Target down-payment or equity picture
- A rough reserve goal so a quote doesn’t stretch you thin
- Questions for the lender: loan options, estimated closing costs, how long a quote stays usable
Journal home guides for calm next reads: Home guides
How to use national jobs/rate headlines without over-reading them
Headlines mix three different clocks. Keep them apart:
- Jobs and wages (BLS) — labor-market health; not your mortgage rate
- Mortgage rates (market surveys such as Freddie Mac PMMS) — what borrowers are seeing nationally; not the Fed’s overnight policy range
- Fed policy rate (FOMC) — influences conditions over time; it is not a 30-year mortgage rate
A solid jobs print can support income confidence. It does not guarantee cheaper financing.
For background on the difference between jobs data, mortgage rates and monetary policy, see our August 2026 housing-budget explainer.
Official background sources: BLS Employment Situation · Freddie Mac PMMS · Federal Reserve FOMC materials
Budget considerations in Cypress, Bear Creek and Spring
In northwest-metro pockets such as Cypress, Bear Creek, or Spring, fall shopping often means juggling commute, HOA dues, and utility seasonality alongside the mortgage quote. Use those lifestyle costs in your budget sheet—compare property traits and carrying costs, not people. Neighborhood planning: Find a neighborhood that feels like you
Next steps
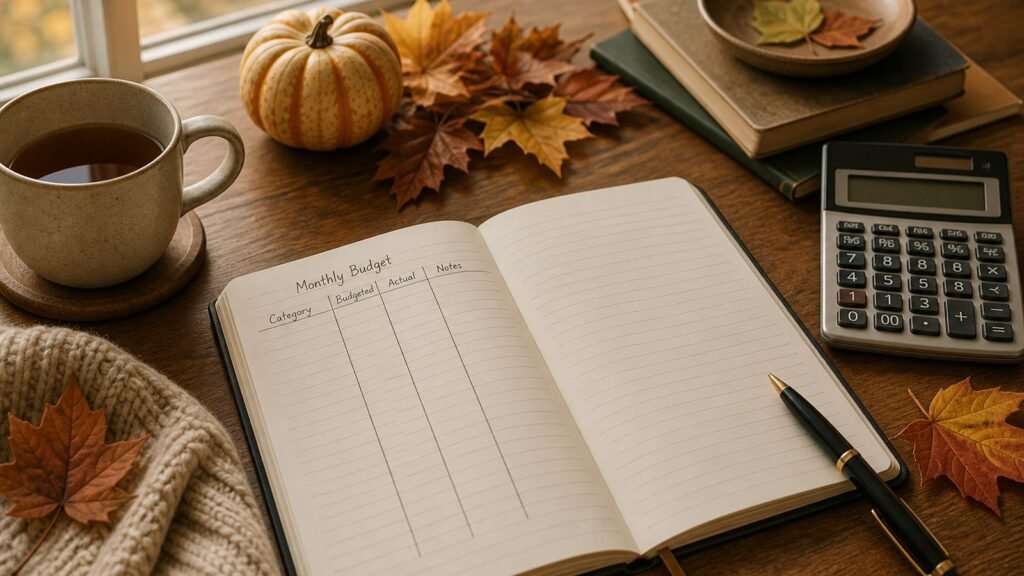
- Build the four-dial sheet (income, debts, reserves, lender quote)
- Ask your lender for a written estimate you can revisit in fall
- Only then map showings or a refinance chat to numbers you trust
About this series: About the Journal
Contact Aurhomes Group about your next move: aurhomesgroup.com/contact · (281) 724-3966.